Article
The Emperor Has No Clothes
Retirement realities on a fixed income
Michael K. Cobb · Oct 9, 2026
Saving is great. But if we start now, can we really save enough to live well in our old age?
The numbers below argue that for most people, the honest answer is no. The alternative is Social Security. Isn’t that a sad sentence? And it gets even sadder when you calculate the cost of what we need and use daily, not the CPI Index. Since 2000 the price of televisions has fallen 98% and toys 74%, while hospital services rose 281% percent. Both go in the same basket.
Now, let me say right up front, that I’m not an investment advisor. I don't have a way for most Americans to close that savings gap. What do have, is an alternative way of seeing a solution to the problem.
Think outside the box… or live in a harsh reality that is going to get worse.
Fair warning. The next few paragraphs may upset you. They should.
Should I buy my medicine or keep the heat on?
Some people already ask themselves that every winter. Many more are going to be asking this same question soon.
The gap between what Americans have saved and what they will need was $28 trillion in 2015. By 2050 it will be $137 trillion. That is $400,000 for every one of the 343 million people alive in America today.
But not everyone will be retired in 2050. Divide it by the 82 million who will be 65 or older, and the shortfall per person is $1.67 million. $1.67M. That should stagger you.
When old people start dying because they can't afford medicine or heat, the government will step in. (Oh goodie.) They'll have to. Old people vote.
Those words are harsh. So is the situation
Last time I wrote something like this, I got a few love letters telling me I was heartless. Really? All I did was point out that the emperor has no clothes. He's naked.
Here's more proof.
Nearly half of American workers, 46%, have never once sat down and worked out what they will need for retirement. The median savings for working Americans aged 21 to 64, counting the millions with nothing, is $955.
Not $955 thousand. Nine hundred and fifty-five dollars. $955.00. Shocking, don’t you agree?
To close the savings gap, the average person would need to save $55,700 a year, every year, for thirty years. Social Security's own W-2 records show that about 61 percent of American wage earners, some 107 million people, took home less than $55,700 in all of 2023.
The savings target needed for a comfortable life in retirement is larger than most people’s paycheck.
You can't save more than you make.
So, the belt gets tightened. And tightened. And tightened again. If nothing changes, nothing changes.
Then what about Social Security?
The average retired worker collects $2,071 a month.
Tight, but survivable, today. Now run it forward thirty years.
There's a cost-of-living adjustment, so it keeps up with inflation. Right?
Don't believe it. The COLA is calculated from an index built around working-age urban wage earners, not retirees. Retirees spend far more of every dollar on health care, prescriptions and housing. Stuff that actually costs far more each year than stuff in the CPI index which includes dashboard cams and big screen TVs. Remember?
Look at what that means. Since 2000, overall inflation ran 92.6 percent. Hospital services rose 281.4 percent. Medical care services, 147 percent. Housing, 111.4 percent.
Wages rose 131.1 percent, which sounds fine until you notice wages didn’t keep up with the items most old people are going to need a lot of. Neither did the COLA for Social Security. See how this is a downward spiral for half of working Americans with under $1,000 in savings?
That is why the Social Security check keeps up on paper and the index, but not in the pharmacy.
The Senior Citizens League ran the math this year. Over the past decade the average Social Security benefit has lost 13.7 percent of its purchasing power. To recover it, the average check would have to rise by $295.85 a month.
So, the money is already short, and what arrives buys less every year.
Think outside the box
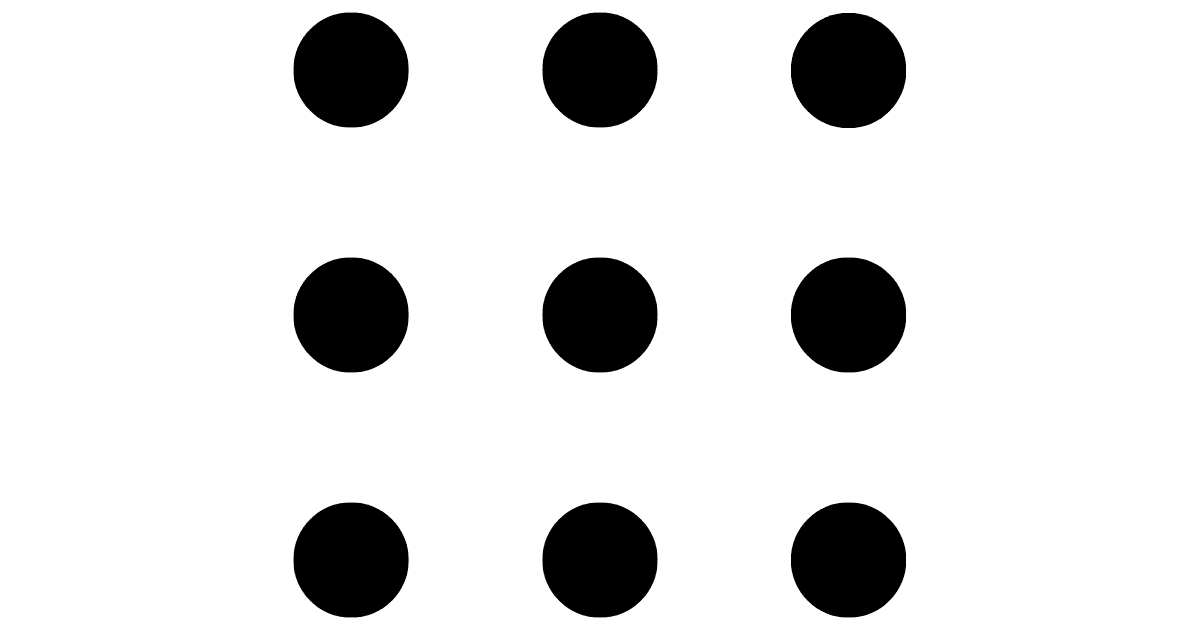
Have you seen this puzzle? Nine dots in a square. Join them all with four straight lines, without lifting your pen.
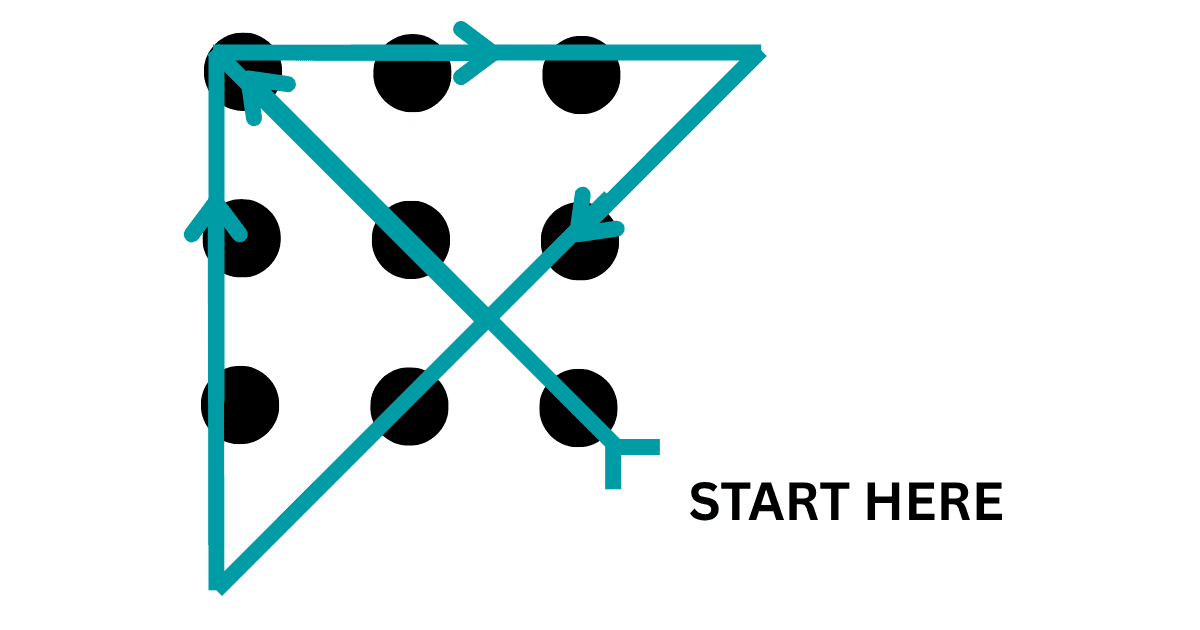
Can you do it all inside the square? No. And, that is the lesson. Solution at the end of the article.
The fixed income problem is the same shape. Inside the box, the only move is save more. We’ve already established that most people can't. The other option? Spend less which is increasingly harder.
Outside the box there are two excellent options.
First: Reduce what you spend. International Living's 2026 Global Retirement Index found that in the right places abroad, a couple can live comfortably from about $1,900 a month, housing included. Set that against the $2,071 the average retiree collects and the arithmetic changes completely. A great life within the Social Security budget. This is a wonderful idea that most Americans have never seriously considered.
Second: Invest outside the box.
Look again at the shape of this problem. It is not a cash flow problem. You are being asked to preserve purchasing power across twenty-five or thirty years, and almost nothing in an ordinary portfolio is built to do that. Cash loses. Bonds cannot keep pace. Equities do it well and then don't, on a schedule nobody controls.
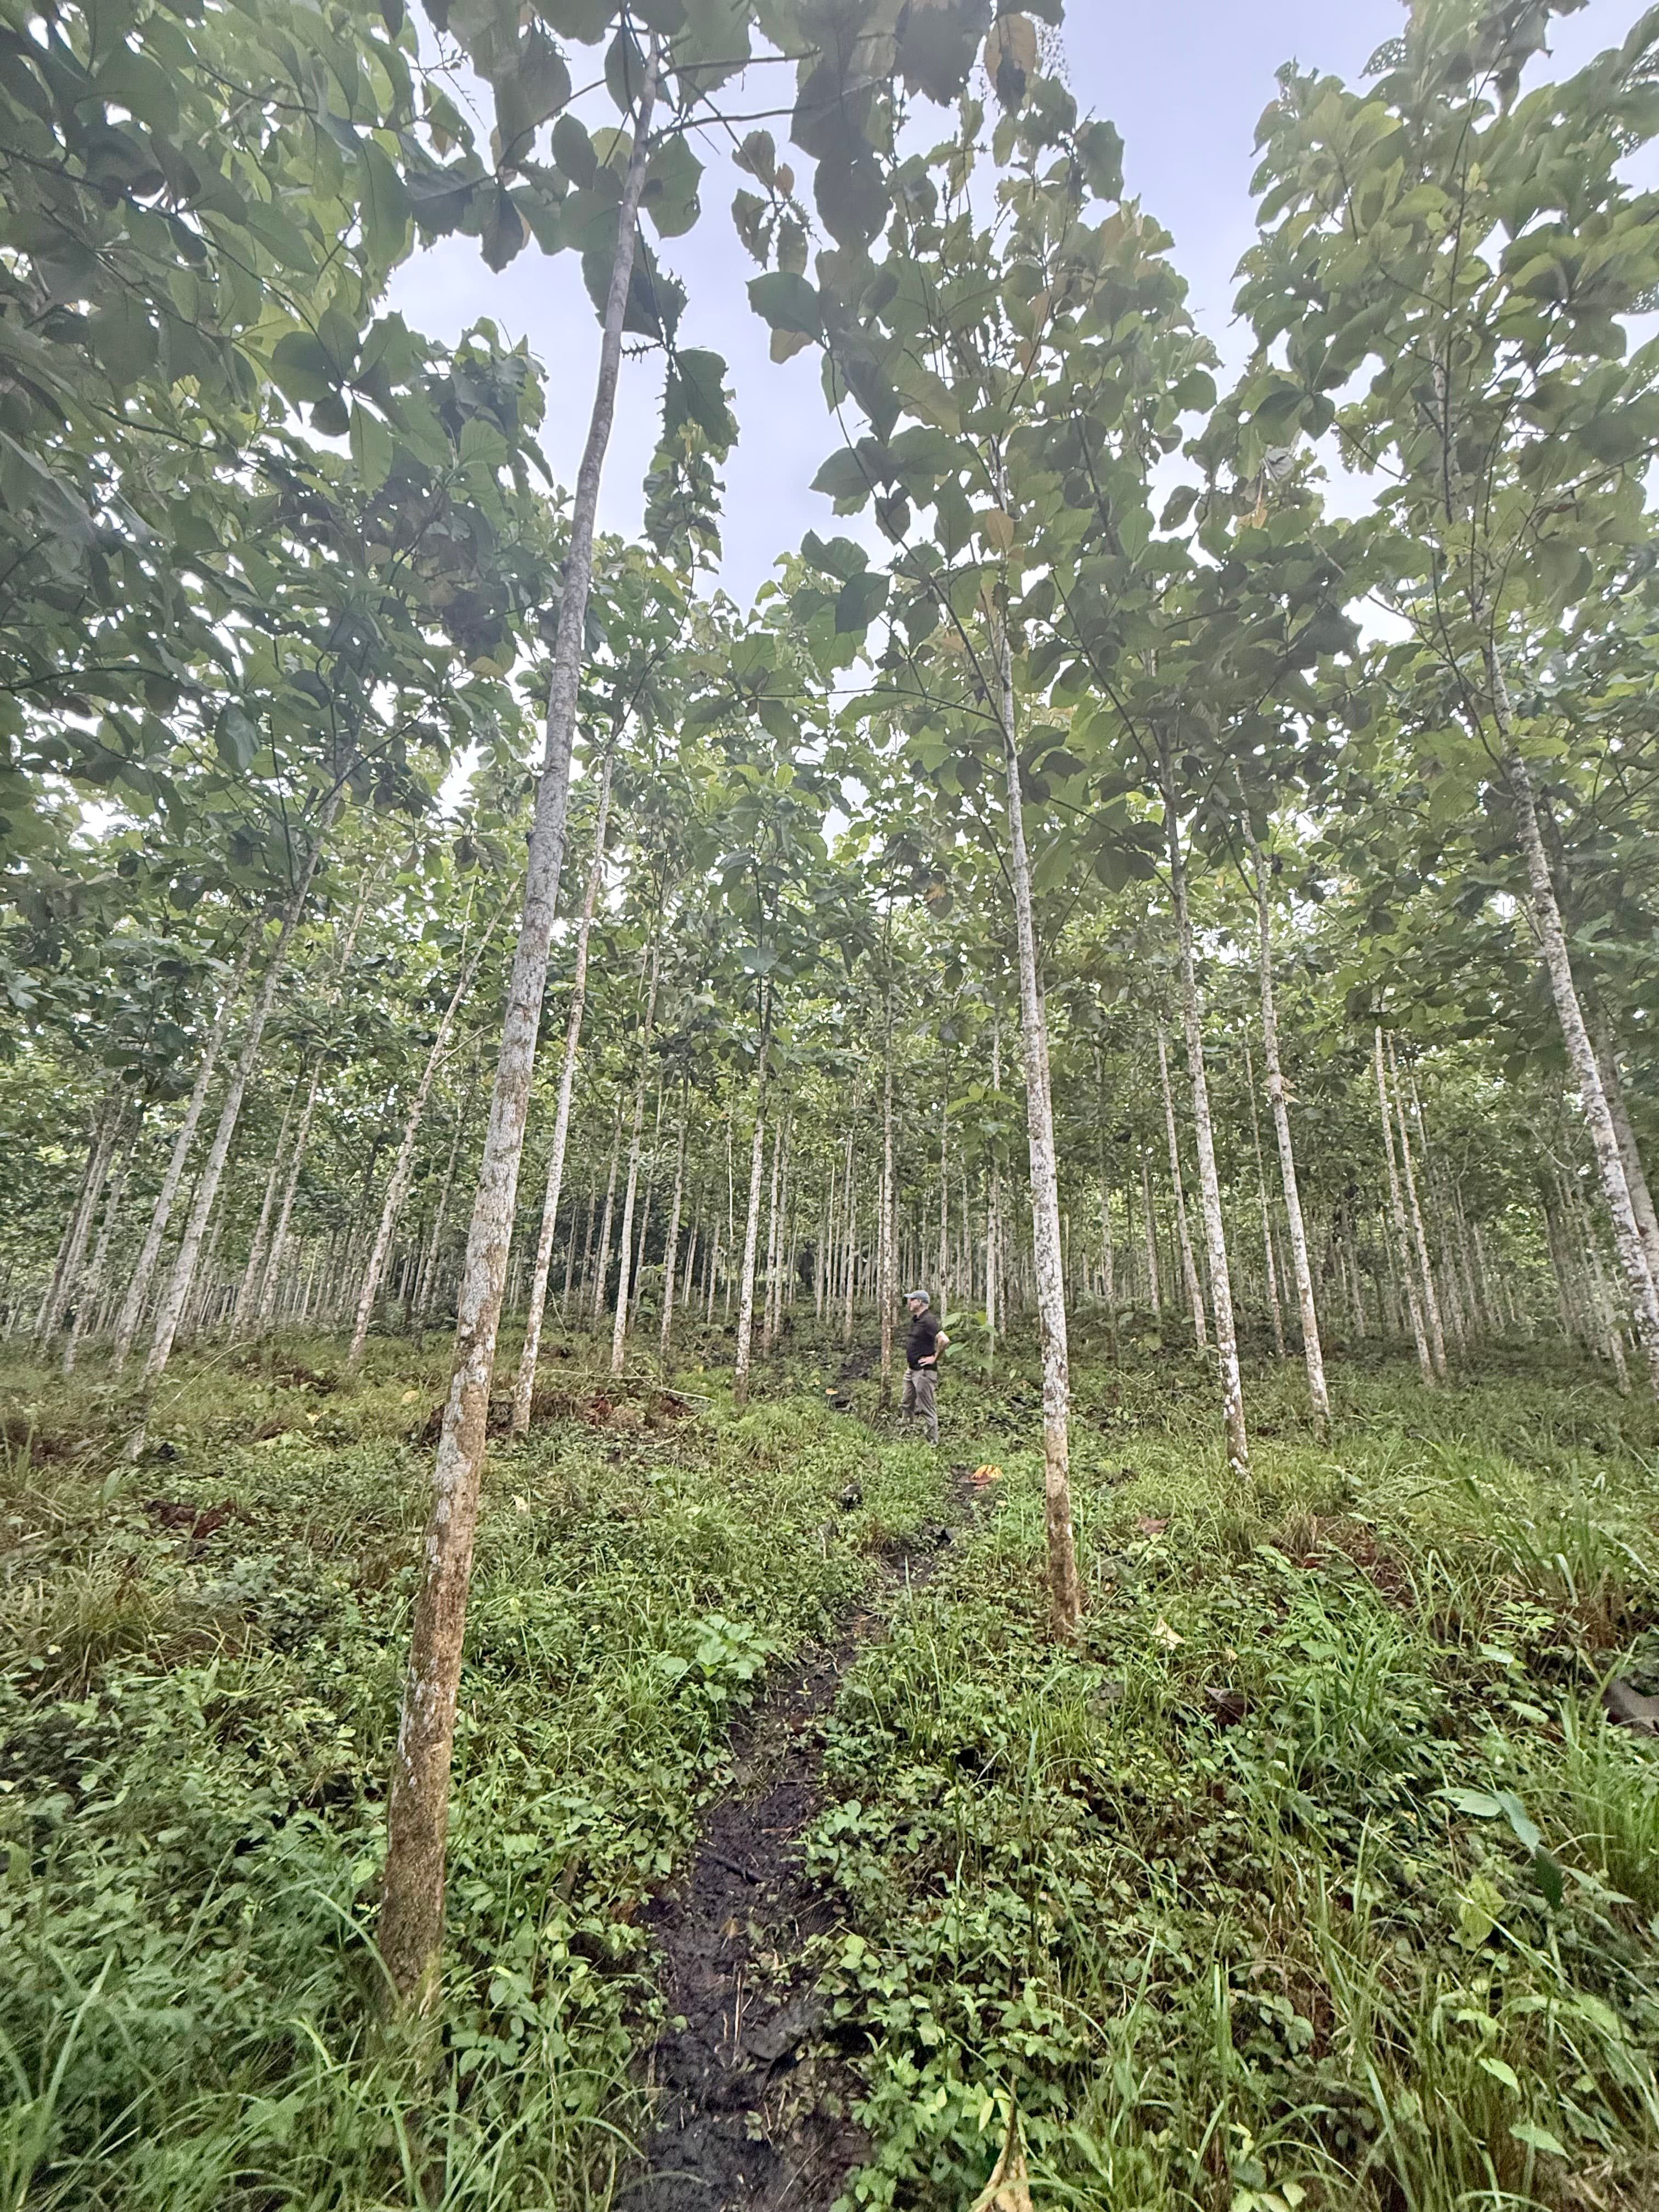
So, the real question is: what do you own that runs on the same time clock you need for retirement cash flow? I've been working in Latin America since 1996. Starting in 1999, I've been growing Teak Timber in Panama on ground that used to be a cattle pasture. That first farm is in its first harvest cycle right now.
Here is what a tree does that a portfolio does not.
The trees grew through 2008 while the stock and real estate markets came apart. They grew through Covid in 2020. Biological growth is not correlated to anything, because it isn't a market. It's a tree.
Timber is illiquid, it is a 20-to-25-year hold with no secondary market, and the industry has a documented history of overselling it. The FAO has said in print that teak has been promoted on growth and pricing scenarios unrealistic enough to mislead careful buyers.
Ask them of anyone selling you anything. Including me.
If you are in your 30s or 40s, staring at a thirty-year horizon and a shrinking check, it is worth understanding what a long-duration hard asset can and cannot do before you rule it out.
If you are already in retirement, and have more than you need, setting up kids and grandkids for the coming belt tightening, might be the legacy gift they don’t know they need.
Chances are you already understand the scenario presented here. You know the emperor has no clothes. Do someone else a favor and pass this along to others in your network thinking about their retirement. It’s a simple act of giving that could have profound impact.
Until next time, all the best,
Mike Cobb, Teak Hardwoods
P.S. I am working on a list of twelve questions anyone should ask a timber seller, with my own answers about our farms. Including the awkward ones. More on that soon.
P.P.S. Puzzle solution here.
Questions This Raised?
The best decisions start with good questions. Bring yours, and let's see where they lead.